
Last Updated on 18 September 2026
Introduction
Choosing a mutual fund for long-term investing is not simply about looking at its past returns. Investors also need to understand the fund’s investment strategy, portfolio, expense ratio, risk, fund management, diversification and whether it fits their financial goals. For Aditya Birla Sun Life Flexi Cap Fund review, you should know that it is an equity mutual fund that can invest across large-cap, mid-cap and small-cap companies. This gives the fund manager flexibility to change the portfolio’s market-cap exposure depending on the investment strategy and market conditions.
The scheme was allotted units in August 1998 and is benchmarked against the Nifty 500 TRI. As of July 31, 2026, the fund had month-end assets under management of about ₹28,112 crore and held 83 securities.
This Aditya Birla Sun Life Flexi Cap Fund review looks at the scheme from a long-term investor’s perspective. We will examine its portfolio, fund managers, expenses, investment approach, risk, SIP requirements, taxation, advantages and limitations.
The objective is not to tell you whether you should buy the fund. Instead, the aim is to give you enough information to decide whether this type of flexi-cap fund fits your own portfolio and risk tolerance.
For detailed information about SBI Small Cap Fund Review
Aditya Birla Sun Life Flexi Cap Fund: Key Details
Here is a quick overview of the scheme based on information available for July 2026.
| Particular | Details |
|---|---|
| Fund name | Aditya Birla Sun Life Flexi Cap Fund |
| Category | Flexi Cap Fund |
| Fund type | Open-ended equity scheme |
| Allotment date | August 27, 1998 |
| Benchmark | Nifty 500 TRI |
| Fund managers | Harish Krishnan and Dhaval Joshi |
| AUM | ₹28,112.33 crore |
| Number of securities | 83 |
| Minimum SIP | ₹100 |
| Minimum additional investment | ₹100 |
| Entry load | Nil |
| Exit load | 1% if redeemed/switched on or before 90 days; Nil thereafter |
| Direct plan base expense ratio | 0.71% |
| Regular plan base expense ratio | 1.36% |
| Risk category | Very High |
The above figures are time-sensitive. The AMC’s July 2026 data states that the expense ratio figures are base expense ratios and exclude certain brokerage, transaction costs and statutory levies. Therefore, investors should check the latest factsheet rather than relying permanently on the figures above.
What Is Aditya Birla Sun Life Flexi Cap Fund?
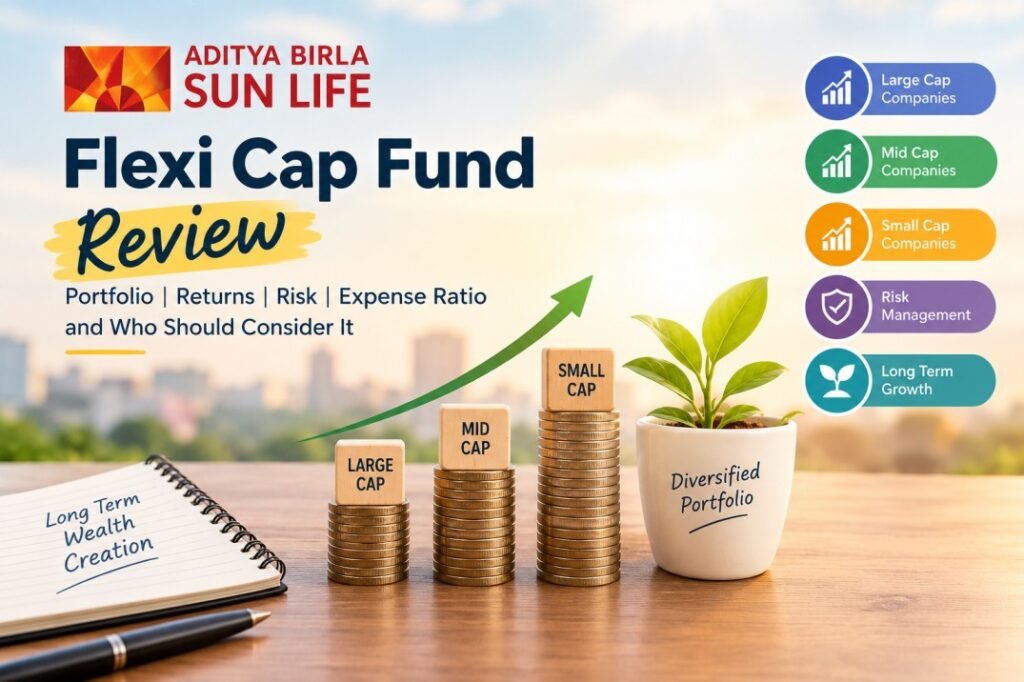
Aditya Birla Sun Life Flexi Cap Fund is an equity mutual fund belonging to the flexi-cap category.
A flexi-cap fund has the flexibility to invest across large-cap, mid-cap and small-cap companies. Unlike a large-cap fund, for example, it does not have to remain focused primarily on the largest companies.
This flexibility allows the portfolio manager to allocate capital across different segments of the equity market.
The scheme’s stated objective is long-term capital growth through investment in equity and equity-related instruments across large-, mid- and small-cap companies. The AMC also explicitly states that the scheme does not guarantee returns.
What does “flexi cap” mean?
Suppose an investor wants exposure to:
- Large established companies
- Mid-sized companies with potential for expansion
- Smaller companies with higher growth potential
Buying separate funds for each category can make the portfolio more complicated.
A flexi-cap fund can provide exposure to all three segments within one scheme, while the fund manager determines the allocation.
However, this flexibility does not eliminate risk. Equity markets can fall sharply, and the value of a flexi-cap fund can decline substantially during market corrections.
For detailed information about Axis Small Cap Fund Review
Why Does This Fund Matter to Long-Term Investors?
A major challenge for individual investors is deciding how much to allocate to large-, mid- and small-cap stocks.
Market conditions can change over a period of several years. One market segment may perform strongly while another may struggle.
A flexi-cap strategy gives the fund manager the ability to adjust the portfolio instead of following a fixed market-cap allocation.
For example, a portfolio could have a relatively larger allocation to large companies during one period and increase exposure to mid- or small-cap companies at another point.
This can be useful for investors who want active management across market-cap segments without maintaining several separate equity funds.
But investors should remember that flexibility is a strategy feature, not a guarantee of better performance.
For more information about Parag Parikh Flexi Cap Fund Review
Investment Objective and Strategy
The fund’s investment objective is long-term capital growth through equity and equity-related instruments across large-, mid- and small-cap companies.
As a flexi-cap fund, the portfolio can change over time.
The July 2026 portfolio shows that the scheme was diversified across several sectors, including:
- Banking
- IT software
- Retail
- Finance
- Automobiles
- Pharmaceuticals
- Insurance
- Petroleum products
- Healthcare
- Industrial products
- Consumer durables
- Telecommunications
The banking sector represented about 19.03% of net assets in the July 2026 portfolio.
This illustrates an important point: although a flexi-cap fund is diversified, it can still have meaningful exposure to particular sectors.
For detailed information about Best Flexi Cap Mutual Funds in India
Aditya Birla Sun Life Flexi Cap Fund Portfolio
Portfolio construction is one of the most important areas to examine in a mutual fund review.
As of July 31, 2026, the fund held 83 securities. Its largest sector exposure was banking at 19.03% of net assets. IT software represented 7.55%, while retailing represented 6.25%.
Some of the larger individual holdings included:
| Holding | Approx. portfolio weight |
|---|---|
| ICICI Bank | 6.05% |
| Kotak Mahindra Bank | 3.24% |
| HDFC Bank | 3.19% |
| State Bank of India | 2.23% |
| Infosys | 2.28% |
| HCL Technologies | 1.97% |
| Tech Mahindra | 1.66% |
| Persistent Systems | 1.65% |
| Reliance Industries | 2.65% |
These figures are from the July 31, 2026 portfolio and can change with subsequent portfolio rebalancing.
What does this portfolio tell investors?
The portfolio is not dependent on just one company.
The top 10 holdings together accounted for about 27.85% according to an independent portfolio data source using the July 2026 portfolio.
At the same time, banking exposure was significant. This means investors should not assume that diversification means every sector receives an equal allocation.
Market-Capitalisation Allocation
One of the key features of a flexi-cap fund is its ability to move between market-cap segments.
The July 2026 portfolio data showed approximately:
| Market-cap segment | Approx. allocation |
|---|---|
| Large Cap | 55.65% |
| Mid Cap | 27.04% |
| Small Cap | 15.50% |
| Other/cash | Balance |
These figures are based on July 31, 2026 portfolio data and can change over time.
The relatively significant large-cap exposure means the portfolio was not exclusively focused on mid- and small-cap stocks.
At the same time, more than 40% was represented by mid- and small-cap exposure in that snapshot.
This combination can provide broader participation across different parts of the equity market, but it can also introduce additional volatility compared with a portfolio concentrated in large-cap companies.
Fund Managers
The scheme is currently managed by Harish Krishnan and Dhaval Joshi.
According to the AMC’s July 2026 fund information:
- Harish Krishnan has been managing the fund since November 3, 2023.
- Dhaval Joshi has been managing the fund since November 21, 2022.
When evaluating a mutual fund, investors should distinguish between the fund’s long historical record and the tenure of the current fund managers.
The scheme has existed since 1998, but the current managers have been associated with the scheme for a much shorter period.
Therefore, it would be misleading to attribute the entire historical performance record of the scheme to the current management team.
For detailed information about Multicap vs Flexicap Funds
Aditya Birla Sun Life Flexi Cap Fund Performance
Past returns are one of the most searched aspects of any mutual fund review, but they should be interpreted carefully.
The Direct Growth option had a NAV of ₹2,199.23 as of July 31, 2026, while the Regular Growth option had a NAV of ₹1,952.00. NAV differences between plans should not be interpreted as one plan being automatically better because each plan has its own history and expense structure.
More recent data showed that the Direct Growth option’s NAV was ₹2,141.17 on September 15, 2026. A third-party data source reported approximately 5.54% one-year, 13.41% three-year annualised and 10.99% five-year annualised returns as of that date.
These numbers should not be treated as permanent performance figures.
Why shouldn’t investors look only at returns?
Consider two hypothetical funds:
- Fund A earns 14% with very high volatility.
- Fund B earns 13.5% with lower volatility.
An investor might prefer one or the other depending on their objectives and risk tolerance.
Returns need to be considered alongside:
- Benchmark performance
- Category performance
- Rolling returns
- Volatility
- Drawdowns
- Portfolio concentration
- Expense ratio
- Investment horizon
A single one-year return number does not provide enough information to evaluate an equity mutual fund.
Risk and Volatility
Aditya Birla Sun Life Flexi Cap Fund is an equity fund and carries a Very High risk classification.
The AMC’s July 2026 data reported:
- Standard deviation: 14.64%
- Sharpe ratio: 0.67
- Beta: 0.95
- Treynor ratio: 0.11
- Information ratio: 0.89
These measures were calculated using three years of monthly returns, with the risk-free rate assumption specified by the AMC.
What does beta of 0.95 mean?
Beta is a measure of how a fund’s movements have historically compared with its benchmark.
A beta around 1 generally indicates movement broadly similar to the benchmark.
A beta below 1 does not mean that the fund cannot fall significantly. It only describes historical sensitivity relative to the benchmark over the measurement period.
What is standard deviation?
Standard deviation is commonly used as a measure of return volatility.
A higher standard deviation generally indicates greater variability in historical returns.
It does not predict exactly how much the fund will rise or fall in the future.
Expense Ratio
Expense ratio is an important factor for long-term investors because fund expenses reduce the amount of money that remains invested.
As of July 31, 2026, the AMC reported a base expense ratio of:
- Direct Plan: 0.71%
- Regular Plan: 1.36%
The AMC notes that the base expense ratio excludes brokerage incurred towards execution of trades, transaction costs and applicable statutory levies.
Direct vs Regular Plan
The underlying portfolio is common, but the plans have different expense structures.
A direct plan is generally purchased without a distributor, while a regular plan involves distribution arrangements.
For long-term investors, even a seemingly small annual cost difference can become meaningful because expenses compound over time.
Investors should therefore compare the current expense ratio rather than relying on an old figure.
For detailed information about Best Mutual Funds for SIP for Beginners in India
SIP Investment
The scheme allows SIP investments with a minimum SIP amount of ₹100, according to the AMC’s July 2026 information.
This makes the fund accessible to investors who want to start with a relatively small amount.
Example
Suppose a beginner starts a hypothetical SIP of ₹2,000 per month.
The investor contributes:
₹2,000 × 12 = ₹24,000 per year
Over five years, the total contribution would be:
₹24,000 × 5 = ₹1,20,000
The actual value after five years will depend on market performance. It could be higher or lower than the amount invested.
This is why SIP should not be described as a method that eliminates market risk.
A SIP simply spreads purchases over time.
You may calculate your investment through SIP by using our Free SIP Calculator.
Exit Load
According to the AMC, the fund has:
- Entry load: Nil
- Exit load: 1% if units are redeemed or switched out on or before 90 days from allotment
- After 90 days: Nil
This is particularly relevant for investors who may need their money soon.
A flexi-cap fund is generally more appropriate for long-term goals than for money that may be required in the near future.
Taxation
For equity-oriented mutual funds, taxation depends on the holding period and applicable tax rules.
Under the tax rates applicable from July 23, 2024, AMFI’s published information states that:
- Short-term capital gains on equity-oriented mutual funds are taxed at 20%.
- Long-term capital gains are taxed at 12.5% on gains exceeding the applicable ₹1.25 lakh annual exemption threshold, subject to the applicable conditions.
- Long-term treatment generally applies when equity-oriented mutual fund units are held for more than 12 months.
Tax rules can change through future Finance Acts and Budget announcements.
Therefore, investors should verify the latest tax rules with the Income Tax Department, AMFI or a qualified tax professional before making decisions.
Pros of Aditya Birla Sun Life Flexi Cap Fund
1. Flexible market-cap allocation
The fund can invest across large-, mid- and small-cap companies.
This gives the portfolio manager flexibility to change exposure over time.
2. Diversified portfolio
The scheme held 83 securities in the July 2026 portfolio.
This provides exposure to a broad collection of businesses rather than relying on a handful of stocks.
3. Long operating history
The scheme’s allotment date goes back to August 1998.
A long history provides investors with more historical information to study, although historical performance should never be treated as a guarantee of future returns.
4. Low minimum SIP
The AMC lists a minimum SIP of ₹100, making the scheme accessible to small investors.
5. Multiple sectors
The portfolio spans banking, technology, healthcare, automobiles, retail, industrials, insurance and other sectors.
Cons and Limitations
1. Equity-market risk
This is an equity fund with a Very High risk classification.
The NAV can fall considerably during market corrections.
2. Sector concentration
Banking accounted for about 19% of net assets in July 2026.
Therefore, investors should not assume that the portfolio has equal exposure to every industry.
3. Active-management risk
The fund’s results depend partly on portfolio-management decisions.
A manager can make allocation decisions that differ significantly from the benchmark.
4. Expense ratio
The regular-plan expense ratio was considerably higher than the direct-plan base expense ratio in the July 2026 data.
Investors should understand the cost difference before choosing a plan.
5. Not suitable for short-term goals
A stock-market correction can occur at any time.
Someone investing money needed for a house payment, emergency expense or other near-term requirement could be forced to redeem during a market decline.
Who Should Consider This Fund?
A flexi-cap fund may be worth researching for investors who:
- Have a long investment horizon
- Understand equity-market volatility
- Want exposure to large-, mid- and small-cap companies
- Prefer an actively managed portfolio
- Want to use SIP for long-term wealth creation
- Can tolerate temporary losses
- Do not need the invested money in the short term
The important point is that suitability depends on the investor’s complete financial situation.
Who Should Avoid or Be Cautious?
This type of fund may not be appropriate for someone who:
- Needs the money within a short period
- Cannot tolerate significant temporary losses
- Is investing an emergency fund
- Expects guaranteed returns
- Wants capital protection
- Is uncomfortable with active fund management
- Already owns several overlapping diversified equity funds
An investor should not select a fund simply because its recent returns look attractive.
Aditya Birla Sun Life Flexi Cap Fund vs Nifty 50 Index Fund
One useful comparison is between an actively managed flexi-cap fund and a passive Nifty 50 index fund.
| Feature | Flexi Cap Fund | Nifty 50 Index Fund |
|---|---|---|
| Management | Active | Passive |
| Market-cap exposure | Large, mid and small | Large-cap Nifty 50 |
| Portfolio decisions | Fund manager | Index methodology |
| Flexibility | Higher | Lower |
| Diversification | Across market caps | 50 large companies |
| Fund-management risk | Present | Lower active-management risk |
| Expense | Usually higher than low-cost index funds | Usually lower |
| Tracking error | Not applicable in same way | Important consideration |
| Investor choice | Depends on active strategy | Depends on index exposure |
Neither approach is automatically suitable for every investor.
The choice depends on whether the investor wants active portfolio management across market caps or straightforward passive exposure to the Nifty 50.
Practical Example: How to Evaluate the Fund
Suppose Rahul is 30 years old and wants to invest ₹5,000 every month for a long-term goal.
Instead of asking only:
“Has this fund given good returns?”
Rahul could ask:
- What is my investment horizon?
- Can I tolerate a 20–30% temporary decline?
- Do I already own another flexi-cap or multi-cap fund?
- What is the latest expense ratio?
- How has the fund performed against its benchmark over multiple periods?
- Who currently manages the fund?
- What does the current portfolio look like?
- Is the fund’s investment strategy consistent with my objectives?
- What taxes could apply when I redeem?
- Do I need this money in the next few years?
This approach is more useful than choosing a mutual fund based on one recent return figure.
Common Mistakes Investors Should Avoid
Mistake 1: Investing because of past returns
Past performance can change.
A fund that performed strongly in one period may not repeat the same result.
Mistake 2: Ignoring overlap
Holding several flexi-cap, multi-cap and large-cap funds can create significant overlap.
Investors should examine portfolios rather than simply counting the number of funds.
Mistake 3: Choosing the regular plan without understanding costs
Investors should understand how distributor commissions and expenses affect the plan’s long-term cost.
Mistake 4: Stopping SIPs during market corrections
A falling market can be uncomfortable.
However, stopping a SIP purely because the market has declined can turn temporary volatility into a behavioural problem.
Investors should make changes based on their financial plan rather than short-term market emotions.
Mistake 5: Using an equity fund for short-term needs
Money needed soon should generally not be exposed to unnecessary equity-market volatility.
Mistake 6: Checking NAV instead of total performance
A fund with a NAV of ₹2,000 is not automatically more expensive than one with a NAV of ₹20.
NAV alone does not tell you whether a mutual fund is cheap or expensive.
Things to Check Before Investing
Before investing in Aditya Birla Sun Life Flexi Cap Fund, check the latest:
- Portfolio
- Expense ratio
- AUM
- Fund-manager information
- Benchmark
- Riskometer
- Asset allocation
- Top holdings
- Exit-load rules
- Tax treatment
- Direct vs regular plan costs
The AMC maintains official factsheets, portfolio disclosures and scheme documents for investors.
These documents should be treated as the primary source when verifying current fund information.
Key Takeaways
- Aditya Birla Sun Life Flexi Cap Fund is an open-ended flexi-cap equity mutual fund.
- The scheme was allotted on August 27, 1998.
- Its benchmark is the Nifty 500 TRI.
- The fund can invest across large-, mid- and small-cap companies.
- As of July 31, 2026, the fund had AUM of about ₹28,112 crore.
- The portfolio contained 83 securities.
- Banking was the largest sector allocation at about 19.03% in July 2026.
- The direct-plan base expense ratio was 0.71%, while the regular-plan base expense ratio was 1.36% at that time.
- The minimum SIP listed by the AMC was ₹100.
- The fund has a 1% exit load for redemptions/switch-outs on or before 90 days.
- It carries high equity-market risk and is classified in the Very High risk category.
- Past returns should be evaluated against the benchmark and over multiple periods rather than judged from a single year.
- Investors should verify current fund data before investing because portfolio and cost figures change.
Frequently Asked Questions
1. What is Aditya Birla Sun Life Flexi Cap Fund?
It is an open-ended equity mutual fund in the flexi-cap category. The scheme invests across large-cap, mid-cap and small-cap companies with the objective of long-term capital growth.
2. Is Aditya Birla Sun Life Flexi Cap Fund suitable for beginners?
It can be considered by beginners who understand that equity mutual funds can be volatile and who have a sufficiently long investment horizon. Beginners should first understand their risk tolerance and financial goals rather than selecting a fund only on past returns.
3. What is the minimum SIP in Aditya Birla Sun Life Flexi Cap Fund?
The AMC’s July 2026 information lists a minimum SIP of ₹100.
4. What is the expense ratio of Aditya Birla Sun Life Flexi Cap Fund?
As of July 31, 2026, the AMC reported a base expense ratio of 0.71% for the Direct Plan and 1.36% for the Regular Plan. These figures can change, so investors should check the latest factsheet.
5. What is the exit load?
The AMC states that 1% is charged if units are redeemed or switched out on or before 90 days from allotment. After 90 days, the stated exit load is nil.
6. Who manages Aditya Birla Sun Life Flexi Cap Fund?
As per the July 2026 fund information, the fund managers are Harish Krishnan and Dhaval Joshi.
7. What is the benchmark of the fund?
The fund is benchmarked against the Nifty 500 TRI.
8. Does the fund invest in small-cap stocks?
Yes. Flexi-cap funds can invest across large-, mid- and small-cap companies. The July 2026 portfolio had approximately 15.50% exposure to small-cap stocks according to portfolio data.
9. Is the fund tax-free?
No. Capital gains from equity-oriented mutual funds can be taxable depending on the holding period and applicable tax rules. Current tax rules should be checked before redemption. AMFI currently states a 20% short-term capital-gains rate and a 12.5% long-term rate above the applicable exemption threshold for qualifying equity-oriented investments, subject to the relevant conditions.
10. Should I invest in Aditya Birla Sun Life Flexi Cap Fund?
There is no universally suitable mutual fund for every investor. The relevant question is whether the fund’s strategy, risk level, portfolio, costs and investment horizon match your financial objectives. Investors should conduct their own research and consider professional advice where appropriate.
Conclusion
Aditya Birla Sun Life Flexi Cap Fund is a long-running flexi-cap equity mutual fund that provides exposure to large-, mid- and small-cap companies through a single actively managed portfolio.
Its long operating history, broad portfolio and flexibility across market-cap segments make it a fund worth researching for investors who are comfortable with equity-market risk and have a long-term investment horizon.
However, the fund is not a low-risk investment. Its portfolio can experience meaningful declines during market corrections, and its future performance cannot be predicted from its historical record.
The July 2026 portfolio also shows why investors should look beyond the fund’s name. Banking represented a significant allocation, while the portfolio also had exposure to technology, retail, automobiles, healthcare, pharmaceuticals and several other industries.
For an investor considering the scheme, the sensible approach is to examine the latest portfolio, expense ratio, benchmark-relative performance, fund-manager strategy, tax implications and overlap with existing investments.
Most importantly, don’t select a mutual fund simply because it has delivered strong returns in the past. A good investment decision begins with your goal, time horizon and ability to handle risk.
Author Note: I have been investing in the Indian stock market since 2018, with practical experience in mutual funds and equities. For U.S.-focused articles, I research information from official fund providers, regulatory sources, company filings, and other reliable sources. I also use AI-assisted research and writing tools to help organize and explain information, while reviewing the content for accuracy and clarity before publication. This article is intended for educational purposes and is not personalized financial advice.
Disclaimer: The content provided is for educational and informational purposes only and should not be considered financial, investment, insurance, or legal advice.